

Attorney
A deep dive into how Florida’s homestead shield holds up (and where it doesn’t) with married couples, unrelated co-owners, children added to the deed, revocable and irrevocable trusts, land trusts, and Lady Bird deeds
Key Takeaways
- O.J. Simpson’s Florida home illustrates the difference between protection against an unsecured civil judgment and exposure to a valid mortgage foreclosure.
- Co-ownership, a gift to a child and changes in residence can alter the homestead analysis. Each owner’s rights and the type of claim matter.
- A trust or enhanced life estate deed can fit a homestead plan, but its actual terms, retained interests and other legal requirements determine the result.
The O.J. Simpson Story People Get Half Right
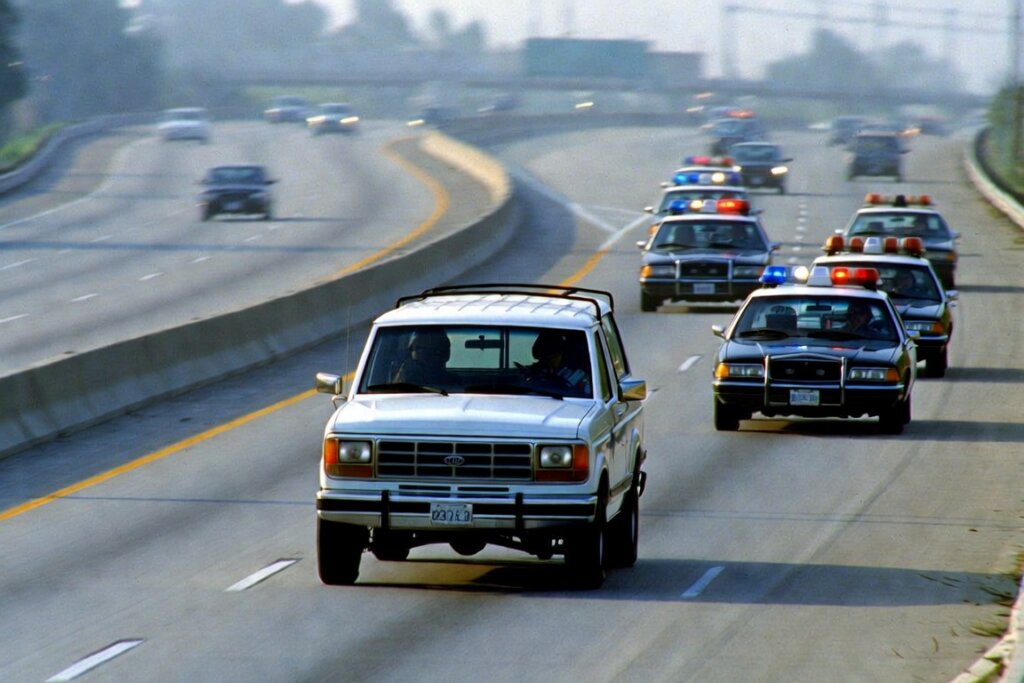
Every Florida asset-protection attorney reaches for this example eventually, and for good reason: O.J. Simpson’s move from California to Florida is the most widely known real-world demonstration of what Florida homestead protection actually does. The trouble is that the popular version of the story stops halfway, and the second half of the story is as instructive as the first.
A civil jury found Orenthal James Simpson liable for the deaths of Nicole Brown Simpson and Ronald Goldman in 1997 and awarded their families $33.5 million in damages. See the Associated Press account of the civil judgment. His Brentwood, California home was sold at a foreclosure auction that July. He bought a home in Kendall, an unincorporated part of Miami-Dade County, and established himself as a Florida resident. Florida’s unlimited homestead exemption protected his house, while the anti-alienation protection afforded to qualifying retirement-plan benefits under federal pension law protected his NFL pension. Consequently, the families could not reach either asset to satisfy their judgment against Simpson. For years, Florida homestead law did its job: The judgment creditors recovered nothing from that house.
Here is the part that tends to get dropped from the story. In 2008, Simpson was convicted on armed robbery and kidnapping charges arising from a Las Vegas incident and was sentenced to state prison in Nevada, where he remained until his 2017 parole. While he was incarcerated, the mortgage on his Kendall house went unpaid. JPMorgan Chase obtained a foreclosure judgment, and the property went through the foreclosure-sale process. Contemporary reports described a 2013 auction; later reporting based on Miami-Dade property records identifies a 2014 sale. The key legal point is unchanged: homestead protection does not defeat a valid mortgage voluntarily granted on the home. The house was not lost to the Brown and Goldman judgment. It was lost through the mortgage lender’s foreclosure.
Simpson did not have a Florida homestead at his death. After his 2017 parole, he settled in the Las Vegas area, where he lived until his death in April 2024. There was no Florida homestead in his estate for his children to inherit, protected or otherwise. His Nevada estate later accepted a claim of approximately $58 million from Ronald Goldman’s father, although acceptance of the claim does not guarantee payment. See the Associated Press’s estate update.
The fuller history is a useful teaching example. It shows what the protection generally covers, an ordinary unsecured civil judgment, and what it does not cover, a valid voluntary mortgage lien. It also shows why the property and the owner’s circumstances must be reviewed over time. Florida’s protection does not automatically extend to a home in another state. Whether a Florida home has been abandoned, however, depends on the facts; a temporary absence does not necessarily end its protected status.
The Core Protection, in Brief
Article X, Section 4 of the Florida Constitution shields qualifying Florida homestead from forced sale to satisfy most money judgments, with no state constitutional dollar cap. The ownership and residence requirements must be satisfied, and a future intention to move in is not enough by itself. The protected area is generally limited to one-half acre within a municipality or 160 contiguous acres outside one. The exemption arises when its legal requirements are met, without a separate application. Federal law, including bankruptcy limits, can change the result.
Homestead protection does not cover everything. A voluntarily granted mortgage or home-equity lien, unpaid property taxes and government assessments, a properly perfected construction lien, an HOA or condominium assessment lien, a federal tax lien, and an equitable lien imposed because the home was purchased with fraudulently obtained funds can all reach a Florida homestead. Ordinary judgment debts, such as credit-card balances, most malpractice judgments, personal-injury verdicts, and business debts, generally cannot. See Fla. Const. art. X, § 4, 26 U.S.C. § 7403, and Havoco of America, Ltd. v. Hill, 790 So. 2d 1018 (Fla. 2001).
The property-tax side of homestead, including the separate exemption, the Save Our Homes assessment cap, portability between Florida homes, and the property-tax amendment on the November 2026 ballot, is a different legal benefit with its own application process and rules. That side of the analysis is covered in the companion article, “Florida Homestead Protection and Property Tax Exemptions: What Every Homeowner Should Know.” This article focuses on the asset-protection side and, specifically, on how that protection holds up once more than one person, or a trust, is involved in owning the home.
When Two People Own the Homestead Together
Married Couples
When spouses own their homestead as tenants by the entirety – as jointly acquired Florida real estate generally is presumed to be unless the deed shows a contrary intent – the spouses hold the property as a single legal unit. If either spouse qualifies for the homestead creditor exemption, the entire TBE property is ordinarily protected from a separate judgment against either spouse. TBE itself does not protect against an enforceable joint debt owed by both spouses. The separate homestead exemption may still protect a qualifying home from a joint unsecured judgment, subject to the recognized exceptions. See Beal Bank, SSB v. Almand & Associates, 780 So. 2d 45 (Fla. 2001), and the Florida Bar’s analysis of co-ownership and homestead.
This is related to, but analytically distinct from, tenancy by the entirety, a form of marital title that can also protect jointly owned personal property. For a full discussion of how TBE works for jointly titled brokerage and investment accounts, and how to obtain that account title in practice, see the Verras Law guide to tenancy by the entirety brokerage accounts.
Unrelated Co-Owners
Two unrelated people, business partners, unmarried partners, or friends buying a home together do not receive automatic whole-property protection merely because one of them occupies the property. Homestead status is personal to each owner. If both co-owners independently satisfy the homestead requirements, each interest can be protected. If only one qualifies, the other owner’s interest does not receive that person’s homestead exemption merely because the first owner lives there. Family residence, temporary absence and the ownership arrangement may require individual analysis. A creditor that acquires that interest may seek partition and ultimately force a sale of the property. See Tullis v. Tullis, 360 So. 2d 375 (Fla. 1978), and the Florida Bar’s co-ownership analysis.
This is a real and frequently overlooked risk in any arrangement where someone puts a non-occupant’s name on title for financing, convenience, or estate-planning reasons, believing the whole house is protected simply because it is somebody’s homestead. The legal effect of the deed may differ from the family’s intentions.
The Common Mistake: Adding an Adult Child to the Deed
A frequent variation on the same problem, and one I address with clients often enough that it deserves its own heading, is a parent adding an adult child to the home’s deed as a joint tenant with right of survivorship. The intention is usually to avoid probate, simplify the estate, or make sure the child inherits it smoothly. The change can also create ownership, creditor, tax, and benefits issues:
- The child’s new ownership interest may be exposed to the child’s creditors, tax liens or bankruptcy, depending on the claim and any exemption available to the child. A child who lives elsewhere ordinarily cannot simply claim the parent’s homestead protection. A gift from a parent is not automatically marital property in the child’s divorce, but ownership, commingling and later transactions can create additional complications. A creditor that acquires the child’s interest may seek partition. See Tullis v. Tullis. A valid lien may need to be paid, released, avoided, allowed to expire or otherwise resolved before clear title can be delivered.
- Adding the child is generally treated as a completed gift of a share of the home’s value for federal gift-tax purposes. That may require filing IRS Form 709 even when no current gift tax is owed because of the federal lifetime exclusion.
- An outright gift of an ownership interest is an uncompensated transfer subject to Medicaid’s 60-month look-back rule unless a statutory exception applies. See 42 U.S.C. § 1396p(c). A properly drafted enhanced life estate deed, discussed below, is commonly used to avoid making a completed transfer during the owner’s life, but Medicaid eligibility always depends on the deed, the applicant’s circumstances, and the law in effect when benefits are sought.
- Adding one child as a joint tenant with right of survivorship can redirect the home away from other intended beneficiaries. If that child survives the parent and the survivorship arrangement remains effective, the parent’s will generally does not override it. The effect concerns this property; it does not necessarily disinherit the other children from the rest of the estate.
- Adding a joint owner does not automatically reset the Save Our Homes assessment cap. Fla. Stat. § 193.155(3)(a)1.c generally does not treat the addition of another individual to title as a change of ownership when the existing owner remains grantor and grantee, unless the added individual applies for a separate homestead exemption on the property. Losing the Save Our Homes cap is not usually the biggest risk. The exposure to the child’s creditors, potential gift-tax reporting, and Medicaid transfer analysis are.
- It is hard to undo cleanly. Removing a joint owner requires that person’s cooperation and a new deed, and if the relationship has soured or the child is uncooperative, the parent can be left litigating to get their own house back. Once a lien arising from the child’s debts has attached to the parent’s property, it cannot be removed by removing the child from the title.
Lady Bird (Enhanced Life Estate) Deeds
A properly drafted Lady Bird deed, formally an enhanced life estate deed, lets an owner retain broad control during life, including the power to sell, mortgage, or divest the remainderman, while directing the property to pass at death without probate. Florida recognizes these deeds through common-law property principles and title practice; there is no statute expressly authorizing them. See Florida Uniform Title Standards 6.10 through 6.12.
Because the owner retains control during their lifetime, a properly drafted enhanced life estate deed can preserve the owner’s homestead creditor protection and tax exemption when the other eligibility requirements remain satisfied. It can also avoid the immediate completed gift created by adding a child as a present joint owner. For Medicaid transfer-penalty purposes, practitioners generally treat the divestable remainder as an incomplete transfer during the owner’s life, but the federal 60-month look-back statute, available exceptions, the deed language, and the applicant’s circumstances must all be reviewed before Medicaid benefits are sought.
In the rare case of Lady Bird deeds for clients with minor children, the advantages bump up against Florida’s third homestead rule: the constitutional restriction on alienating or devising homestead when the owner has a spouse or minor child. Florida Uniform Title Standard 6.11 specifically warns that transfer-restricted homestead must be considered when an enhanced life estate tenant dies. A married owner ordinarily needs the spouse to join a lifetime conveyance of homestead, and the existence of a minor child prevents a devise even when the spouse consents. Moreover, Fla. Stat. § 732.4017 excludes certain completed inter vivos transfers from the definition of a devise only when the transferor does not retain a power to revoke or revest the property – a condition a Lady Bird deed may not satisfy. An attorney representing a client with a minor child should address Article X, Section 4(c) and Fla. Stat. § 732.4015 expressly rather than assuming probate avoidance ends the inquiry. Avoiding probate does not remove the constitutional homestead restrictions.
Homestead Held in a Revocable Trust
A revocable living trust is the most common way to hold a homestead within a broader estate plan that avoids probate while preserving both creditor protection and the property-tax exemption. For creditor protection, the grantor’s retained right to revoke the trust and reclaim the home supports continued beneficial ownership. See Engelke v. Estate of Engelke, 921 So. 2d 693 (Fla. 4th DCA 2006). For the tax exemption, Fla. Stat. § 196.041 focuses on whether the trust grants the resident a beneficial interest in the property for life, ordinarily expressed through an enforceable lifetime right to use and occupy the home.
Homestead Held in an Irrevocable Trust
People are often surprised to learn that an irrevocable trust can preserve homestead protection at all, since the whole point of many irrevocable trusts is that the grantor has given up control, typically for either estate tax minimization or asset protection purposes. The key is that Florida homestead protection does not require fee simple ownership; a qualifying present beneficial interest, including a life estate, may suffice when the other constitutional requirements are met.
An irrevocable arrangement can preserve homestead status when the resident retains a genuine present possessory or beneficial interest in the home, but the cases must be read carefully. In Cutler v. Cutler, 994 So. 2d 341 (Fla. 3d DCA 2008), the owner conveyed her residence to a land trust subject to a reserved life estate, but she also retained the power to withdraw and appoint the trust principal to herself. The case therefore supports the breadth of interests capable of carrying homestead protection and addresses what happened at death, but it is not a clean example of a conventional irrevocable asset-protection trust. More generally, Southern Walls, Inc. v. Stilwell Corp., 810 So. 2d 566 (Fla. 5th DCA 2002), and Geraci v. Sunstar EMS, 93 So. 3d 384 (Fla. 2d DCA 2012), confirm that fee-simple title is not indispensable to the forced-sale exemption. On the tax side, Robbins v. Welbaum, 664 So. 2d 1 (Fla. 3d DCA 1995), and Nolte v. White, 784 So. 2d 493 (Fla. 4th DCA 2001), recognized homestead tax treatment for qualifying personal-residence trusts with retained possessory rights.
The condition that matters in practice is what the grantor keeps and what the grantor gives up. A documented life estate or equivalent beneficial interest may preserve homestead status. A power to revoke, withdraw principal, or direct the property back to the grantor may preserve ownership for homestead purposes while undermining the non-homestead reasons for calling the arrangement irrevocable. The older bankruptcy decision In re Bosonetto, 271 B.R. 403 (Bankr. M.D. Fla. 2001), took a restrictive view of homestead held in trust, while In re Alexander, 346 B.R. 546 (Bankr. M.D. Fla. 2006), recognized the exemption where the debtor was trustee and primary beneficiary of a revocable trust. By contrast, Elmowitz v. Estate of Zimmerman, 647 So. 2d 1064 (Fla. 3d DCA 1994), rejected a homestead claim where the asserted interest did not grant a genuine present possessory interest in the home. The document’s actual rights, not its label, drive the analysis. Calling a trust “irrevocable” does not make it so, and the label alone creates no homestead rights.
Land Trusts: A Privacy Tool Favored by the Rich and Famous
A Florida land trust places legal and record title in a trustee while the beneficiary holds the rights defined by the trust agreement. The privacy benefit is straightforward: The recorded deed can name the trustee without naming the beneficial owner. A search of property appraiser records in the most expensive neighborhoods in Florida will yield less information about the owners than it would in more modest zip codes. The search results will include numerous versions of “John Q. Lawyer, Esquire, Trustee, XYZ Land Trust.” That is not an accident. The public record points to the lawyer, or some other unrelated third party, while the deed may omit the beneficial owner’s name. Other records or lawful disclosure requirements can still reveal ownership.
An attorney serving as trustee has professional responsibilities, and qualifying confidential legal communications may be privileged. The attorney’s name on the deed does not by itself make all ownership information or trust records privileged; the role being performed and the circumstances of a disclosure request matter. See Fla. Stat. § 90.502; Corry v. Meggs, 498 So. 2d 508 (Fla. 1st DCA 1986), and Coffey-Garcia v. South Miami Hospital, Inc., 194 So. 3d 533 (Fla. 3d DCA 2016). The practical privacy benefit comes from keeping the beneficiary’s name out of a routine deed search, with the limits of that arrangement understood from the outset.
An unrelated professional trustee usually adds expense compared with holding title yourself. The trustee’s duties, compensation and responsibility for tax bills and other correspondence should be agreed upon at the outset; an ongoing legal retainer is not the only possible arrangement. Naming yourself as trustee usually removes the privacy gained from keeping your own name off the deed. Naming a family member may also make the relationship easier to trace, although the practical result depends on the names, records and circumstances.
Land trusts also raised an important homestead question: could a beneficiary who lived in the home still qualify? James H. McKillop II’s The Illinois Land Trust in Florida, 13 U. Fla. L. Rev. 173 (1960), discussed those risks before Florida enacted its land-trust statute in 1963.
In the eighteenth century, Adam Smith wrote in The Wealth of Nations, Book V, Chapter I, Part II, “Of the Expense of Justice”: “Civil government, so far as it is instituted for the security of property, is in reality instituted for the defence of the rich against the poor….” Marx and Engels later made the same point with less tact in The Communist Manifesto: “The executive of the modern State is but a committee for managing the common affairs of the whole bourgeoisie.” Smith and Marx disagreed about nearly everything, but both understood that governments are particularly attentive to rich people.
Florida’s land-trust statute provides an express tax rule for qualifying resident beneficiaries. Under Fla. Stat. § 689.071(8)(h) (originally enacted as chapter 63-468, Laws of Florida, 1963), a beneficiary’s principal residence held through a land trust receives the homestead tax exemption when the beneficiary otherwise qualifies. Although Fla. Stat. § 689.071 expressly preserves the homestead property-tax exemption, it does not guarantee the constitutional homestead protection from creditors. The constitutional question is whether the resident beneficiary of a land trust holds a genuine present interest in the home sufficient to satisfy Article X, Section 4. Florida courts have repeatedly held that a home does not lose its homestead character merely because legal title is held in trust. In Cutler v. Cutler, 994 So. 2d 341, 343–44 (Fla. 3d DCA 2008), the court recognized homestead status in a residence held through a land trust where the resident beneficiary had reserved a life estate and retained the power to withdraw or appoint principal to herself. As discussed above, those retained powers make it an unreliable example of a conventional irrevocable asset-protection trust. The safest practice is therefore to grant the resident beneficiary an express, continuous lifetime right to use, occupy, and possess the home. No reported Florida appellate decision appears to decide the narrower question whether mere occupancy, coupled only with a land-trust interest expressly classified as personal property, is sufficient, and I would prefer that none of my clients be the test case.
Two other traps remain. Assigning the beneficial interest to an LLC or corporation can jeopardize both benefits. An entity cannot claim an individual’s homestead rights merely by holding title. Any genuine interest retained by the individual, such as a life estate, requires a separate analysis of the particular benefit and governing requirements. And although a transfer between legal and equitable title ordinarily does not reset Save Our Homes when the same person remains entitled to the exemption, a genuine change in beneficial ownership may reset the cap. See Fla. Stat. § 193.155(3)(a)1.b. The deed, trust agreement, beneficial ownership, and homestead application have to tell the same story, so the assistance of an experienced attorney is critical.
While I have drafted many land trusts and served as trustee, for those of my clients who are not celebrities and have no compelling reason to keep their home address private, I usually advise them against paying me (or any third-party trustee) merely to keep their own name off the deed to their house. If there is a concrete privacy, security, or business reason, a land trust can be very useful. Without a particular privacy or other planning need, the additional cost and administration may offer little practical benefit.
Practical Guardrails
- Know which kind of creditor you are actually worried about. Homestead protects against most unsecured judgments; it has never protected against a mortgage, a contractor’s lien, an HOA assessment, or the IRS.
- If you co-own your home with anyone other than a spouse, understand that the other owner’s financial problems can become your problem, whether that co-owner is a business partner, an unmarried partner, or your own adult child.
- Before adding a child to your deed to avoid probate, compare the alternatives. An enhanced life estate deed or properly funded revocable trust may achieve the intended transfer at death without making the same present gift of ownership to the child. The deed, retained rights, creditor exposure and Medicaid transfer rules still need individual review. Choose the ownership structure as part of the whole estate plan.
- If your home is in a revocable trust, an irrevocable trust or a land trust, have the actual documents reviewed. Your present rights in the home, the ownership arrangement, residence and other legal requirements determine whether each protection applies.
- If you use a Lady Bird deed and you are married or have minor children, address the spousal homestead rules explicitly rather than leaving it for a title company to discover later.
- Review the plan before a move. Florida homestead protection does not automatically protect a new home in another state. Whether an existing Florida homestead has been abandoned depends on residence, intent, family use and the other facts; temporary absence is not the same as permanent abandonment.
Frequently Asked Questions
Did homestead really protect O.J. Simpson’s house from the Brown and Goldman judgment?
Yes, for the years he owned and lived in the Florida home. It did not protect the home from the mortgage lender, which foreclosed years later while he was imprisoned in Nevada, and it did not exist at all by the time he died in 2024 as a Nevada resident.
Can a judgment against my spouse force the sale of our jointly owned home?
If spouses hold a qualifying Florida homestead as tenants by the entirety, the whole property is ordinarily protected from an unsecured judgment against either spouse individually. Mortgages, property taxes and other recognized exceptions require separate analysis.
I own a house with a business partner or an unmarried partner. Is the whole house protected if I live there and they don’t?
Not automatically. Each co-owner’s interest must be evaluated separately. One owner’s qualifying residence does not, by itself, protect another owner’s interest. The second owner may have a different basis for qualifying, but if that interest is not exempt, it may be exposed to that owner’s creditors and a resulting partition claim.
Is it a good idea to add my adult child to my deed so they inherit the house without probate?
It can create risks that are easy to overlook. The child receives a present interest that may face the child’s creditors or bankruptcy; family and divorce consequences depend on the facts. The gift may require Form 709 and may implicate Medicaid’s 60-month transfer look-back, subject to statutory exceptions. An enhanced life estate deed or funded revocable trust can often accomplish the intended transfer at death with fewer of these risks.
Does putting my house in a trust risk losing my homestead protection?
A trust can preserve homestead protection, but correct drafting is only part of the analysis. A properly structured revocable trust and deed can preserve both creditor protection and the tax exemption when the ownership, residence and other requirements remain satisfied. Some irrevocable arrangements also qualify when the resident retains an appropriate present interest. The label alone does not decide the result.
Does a land trust protect my home from creditors and keep my tax exemption?
The tax exemption is specifically addressed by statute for a qualifying individual beneficiary. Creditor protection is not guaranteed merely by the land-trust label; it depends on whether the beneficiary holds a genuine present interest in the home sufficient to qualify under Article X, Section 4. See Fla. Stat. § 689.071(8)(h) and Southern Walls. I help clients weigh that privacy benefit against the trustee’s fee and the additional administration.
Does a Lady Bird deed protect my house from my creditors?
No. A Lady Bird deed does not add creditor protection. Its job is to direct who receives the property at death without probate. It may also avoid a completed lifetime transfer for Medicaid purposes, but eligibility depends on the deed, the law then in effect, and the owner’s circumstances.
Can I use a Lady Bird deed to leave my house to one child if I have a spouse or minor children?
Not without addressing Florida’s homestead devise restrictions directly. A Lady Bird deed that ignores those restrictions can be challenged the same way an equivalent will provision could be. If you have a spouse or minor children, you should consult an experienced estate planning lawyer before attempting to convey your homestead by any means.
The Structure Matters as Much as the State You Live In
Florida homestead law offers substantial protection when its constitutional requirements are satisfied. The deed, trust terms, co-owners, and future interests should be reviewed together to preserve the benefits that apply. The right structure depends on what you are actually trying to accomplish and whose creditors, spouse, children, or future claims may become part of the story.
For the property-tax side of homestead, including the Save Our Homes cap, portability, and Amendment 3 on the November 2026 ballot, see the companion article on Florida homestead tax exemptions. For jointly owned investment and brokerage accounts, see the Verras Law guide to tenancy by the entirety.
To review how your home is titled, and how it fits into your broader estate and asset-protection plan, contact Verras Law, P.A. to schedule a consultation.
Updated October 26, 2026.